|
Keys, Closings & Confidence:
Your August Advantage |
|
|
|
|
| Click Here to Schedule Your Consultation Today! |
|
|
Empowering 2,000 Women and Families to achieve homeownership in 2025
Breaking Barriers, Building Dreams – Helping 2,000 Women and Families Become Homeowners in 2025! |
 |
|
Do You Know Someone Ready to Buy a Home?
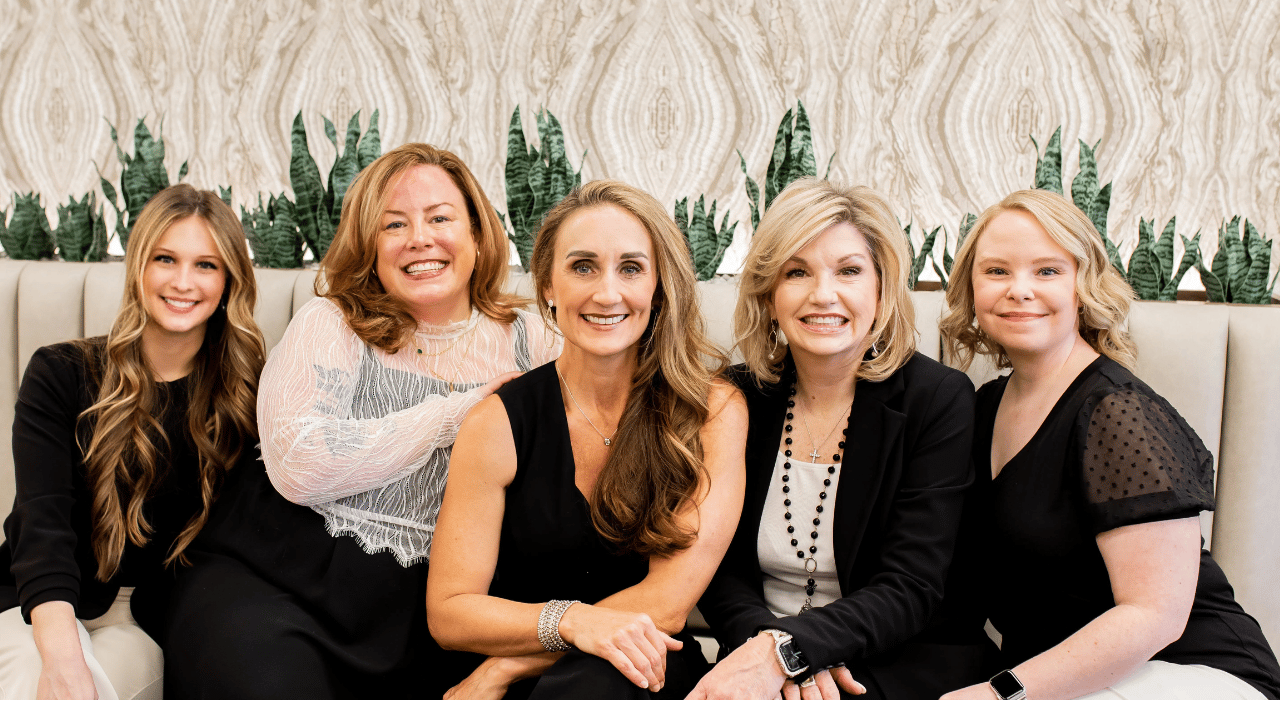
At the heart of our mission is a deep commitment to empowering women and families on their journey to homeownership. While you’ve already taken that step, you might know a friend, family member, or colleague who dreams of owning a home but doesn’t know where to start.
In 2025, our goal is to help over 2,000 women and families achieve this dream. By providing expert guidance, support, and resources, we’re breaking down barriers and making homeownership more accessible than ever.
If someone you know is ready to take the next step, we’d love to help! Send them our way—we’ll walk alongside them every step of the journey.
Let’s make homeownership happen—together |
 |
|
|
|
Times are tough right now, especially for those with high interest debts. What if I told you that by using your mortgage to your advantage, you could eliminate your revolving debts and have more money in your pocket every month? Use some or all of that extra cash to make additional principal payments, shorten the length of your mortgage, pay less in interest over time, and own your home sooner. Even with a higher interest rate, you could potentially shorten your term and build your wealth faster than you are right now. |
|
|
 |
|
FINANCIAL NEWS
Stagflation: What It Is and How to Stay Prepared
You may have seen the word stagflation in recent headlines and wondered what it means. It's not a term we hear often, but it's getting attention again for the first time in decades.
Stagflation is a mix of two words: stagnant and inflation. It refers to a time when prices are rising, economic growth is slowing, and unemployment is climbing. The last time we really saw this combination was back in the 1970s. Just imagine being a homebuyer in 1979, when mortgage rates soared above 11 percent!
So why are people talking about stagflation now? It came up during the Federal Reserve’s May meeting, where some members expressed concern that tariffs and slowing growth could nudge the economy in that direction. At the same time, grocery prices continue to climb and job growth has started to cool.
But let’s be clear—today’s economy looks very different from the 1970s. The energy crisis that drove prices up then isn't an issue now. The U.S. is one of the world’s top energy producers, and electric vehicle charging stations have replaced the long gas lines of the past.
We also have powerful tools that didn’t exist back then. Advances in technology, automation, and global supply chains have helped businesses stay more resilient and adaptable.
Even so, it's always smart to be financially prepared. Whether stagflation happens or not, here are a few ways to stay in a strong position:
· Strengthen your job skills or consider learning new ones
· Cut back on nonessential spending
· Delay large purchases if possible
· Pay off high-interest debt
· Make sure your savings can cover at least three to six months of living expenses
If you're wondering how your budget or financial plans might hold up during uncertain times, we’re here to help. Let’s talk about your options and make sure you're in the best possible position—no matter what the economy brings. |
|
|
 |
|
Mortgage IQ: What the New Tax Bill Means for Homeowners and Buyers
Big news from Washington! The recently passed tax legislation, H.R. 1, also nicknamed the Big Beautiful Bill, could have a direct impact on your real estate journey. Whether you're a current homeowner, future buyer, or investor, here’s what you need to know.
Mortgage Insurance Deductions Are Now Permanent
If you’re within qualifying income limits, you can now permanently deduct your mortgage insurance premiums on your federal taxes. This applies to individuals earning under $175,000 and couples filing jointly under $250,000. It's a small win with the potential for big savings.
Mortgage Interest Deduction Capped at $750,000
The bill makes the cap on mortgage interest deductions for loans up to $750,000 permanent. If you’re purchasing at a higher price point, this is an important factor to consider in your financing strategy.
SALT Deduction Increased Temporarily
From 2025 through 2029, the cap on state and local tax (SALT) deductions will increase to $40,000 per household. A phase-down will begin for incomes over $500,000. If you're in a high-tax state, this could make homeownership even more appealing during those years.
Investors: QBI Deduction Is Here to Stay
If you own investment properties and qualify for the 20% Qualified Business Income deduction, there's good news. This deduction is now permanent, offering valuable long-term benefits for real estate investors.
Down Payment Assistance Remains Local
While no new federal homebuyer or down payment assistance programs were included in the bill, help is still available through state housing agencies, local grants, and employer-assisted programs. We can guide you to the best options in our area.
Whether you're helping clients navigate their next purchase or exploring financing options yourself, staying informed is key. That’s exactly why we're here.
Have questions about how these changes may impact you or your clients? Let’s connect. Our team is ready to provide clarity, strategy, and support every step of the way. We are Your Lending Partner for Life! |
|
|
 |
|
AROUND THE HOUSE
Thinking About a Pool? Make Sure You Add Up the Costs Before You Dive In
Pools are amazing backyard features that can turn your home into a private oasis and boost your popularity with friends and neighbors. Whether you’re buying a home with an existing inground pool or considering installing one, it’s important to know that the upfront price is only part of the story.
Before you take the plunge, here are some key costs and considerations to keep in mind to make the best decision for your budget and lifestyle.
Maintenance Matters
Owning a pool means regular upkeep. Weekly cleaning, balancing the water chemistry, and equipment checks are essential to keep the pool safe and sparkling. If you’re not up for doing this yourself, professional pool maintenance services typically charge fees worth getting estimates on before moving forward.
Repairs Add Up
Pools require repairs from time to time. For example, fixing a leak can run over $700 on average. Detecting and addressing issues early can save money but keep repair costs in your budget.
Safety First
Pools come with safety responsibilities. Installing specialized pool fencing can cost between $15 and $40 per foot, depending on the materials. Adding door alarms and other safety measures helps protect children and gives peace of mind.
Insurance Considerations
Slip-and-fall accidents around pools are more common than you might think. To protect yourself, check your homeowners insurance and consider increasing liability coverage or adding umbrella insurance for full protection.
Will a Pool Add Value?
While pools can enhance your enjoyment, they don’t always add significant resale value. In neighborhoods where pools are common, they may slightly increase home value. But many buyers may see pools as extra expense and risk, which can limit your home’s appeal.
If you’re weighing your options or need help with financing a home with a pool, we’re here to guide you every step of the way. Reach out anytime to talk about how a pool fits into your homeownership plans. |
|
|
 |
|
Did You Know?
Meet the New Generations: Alpha and Beta
Most of us are familiar with names like Millennials and Baby Boomers, even if we occasionally mix up the age ranges. But here’s something you may not know: the newest generation has arrived, and there’s already another one on the way.
Anyone born this year is part of Generation Beta, a group that will include everyone born from 2025 to 2039. In just ten years, it’s expected that Betas will make up more than 16 percent of the global population. This will mark the first time in history that seven generations are living at the same time. Betas will grow up in a world shaped by artificial intelligence, a changing climate, and fast-moving global shifts.
Before them came Generation Alpha, born from 2010 through 2025. That means the oldest Alphas are turning 15 this year. This generation is growing up with smartphones, smart homes, virtual reality, and AI all around them. They’re expected to be the most digitally savvy and diverse generation we’ve seen yet.
Curious where the rest of us fall? Here’s a quick snapshot of today’s generations:
· Generation Z, also called Zoomers, are currently between 13 and 28 years old
· Millennials will be between 29 and 44 years old by the end of this year
· Generation X includes those between 45 and 60 years old
· Baby Boomers range from 61 to 79 years old
· The Silent Generation includes individuals between 80 and 97 years old
Understanding generational trends can be helpful when working with buyers and sellers across all age groups. After all, the future of homeownership includes everyone from Baby Boomers downsizing to Gen Alpha kids growing up in smart homes. |
|
|
|
PERSONAL FINANCES
Buy Now, Pay Later Loans Are Coming to Credit Reports
You’ve probably seen the “Pay in 4” option when you’re shopping online or checking out at your favorite store. Services like Klarna, Affirm, and PayPal’s Pay in 4 have become popular ways to stretch a budget and manage cash flow.
These short-term installment plans, officially known as Buy Now Pay Later or BNPL loans, have gained popularity, especially with younger shoppers and those building credit. Until now, most of these plans have not shown up on your credit report unless the loan goes unpaid and ends up with a collection agency. That is about to change.
FICO recently announced a new credit scoring model that will include BNPL activity. This means lenders may soon be able to see two versions of your credit score: one that includes BNPL usage and one that does not before making a decision.
Currently, Sezzle is the only major BNPL provider that offers optional credit reporting. The others have kept things off your report as long as payments are made on time. However, that flexibility might be shifting.
There are pros and cons. These plans can help consumers who are between paychecks or managing limited incomes. They are also great for building payment history if managed wisely. Traditional lenders sometimes view BNPL usage as a red flag, especially when a borrower has multiple plans open or is using them for everyday purchases like takeout, thanks to partnerships such as Klarna and DoorDash.
What does this mean for you or your clients? It is a good reminder to keep an eye on all credit-related activities and use these tools strategically.
If you have questions about how this could impact your mortgage approval or your clients’ buying power, we are always happy to help. Let’s talk.
|
|
|
|
|
 |
|
Back to School Season: A Time of New Beginnings for Families
As the days grow shorter and the air turns crisper, many families are getting ready for one of the busiest times of the year—back to school. Whether it’s little ones stepping into their classrooms for the first time or teens preparing for their final year of high school, this season is filled with excitement and fresh opportunities.
For parents, it is a time to celebrate milestones and new routines. It can also be a moment filled with mixed emotions, especially for those sending kids off to college for the very first time. Watching your child take that big step toward independence is both thrilling and heartwarming. As one wise soul once said, "Sometimes the smallest step in the right direction ends up being the biggest step of your life."
Back to school means new backpacks, fresh notebooks, and the promise of growth. It also means planning and preparation at home. For families thinking about buying or refinancing to create the perfect learning environment, we are here to help. Whether you need extra space for a homework nook or want to be closer to great schools, we can assist you in finding the right financing solution.
As your trusted lender, we understand how important this season is. We wish all students a successful year ahead filled with discovery, friendship, and joy. To our realtor partners and clients, thank you for trusting us to support your dreams every step of the way.
Here’s to a wonderful back-to-school season and all the new beginnings it brings!
|
|
|
|
RECIPE FOR REAL LIFE
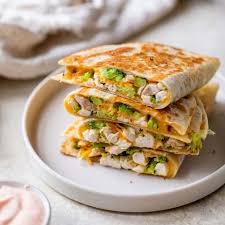
Cheesy Chicken & Broccoli Quesadillas
Quick, kid-approved, and perfect for back-to-school evenings! |
|
|
|
|